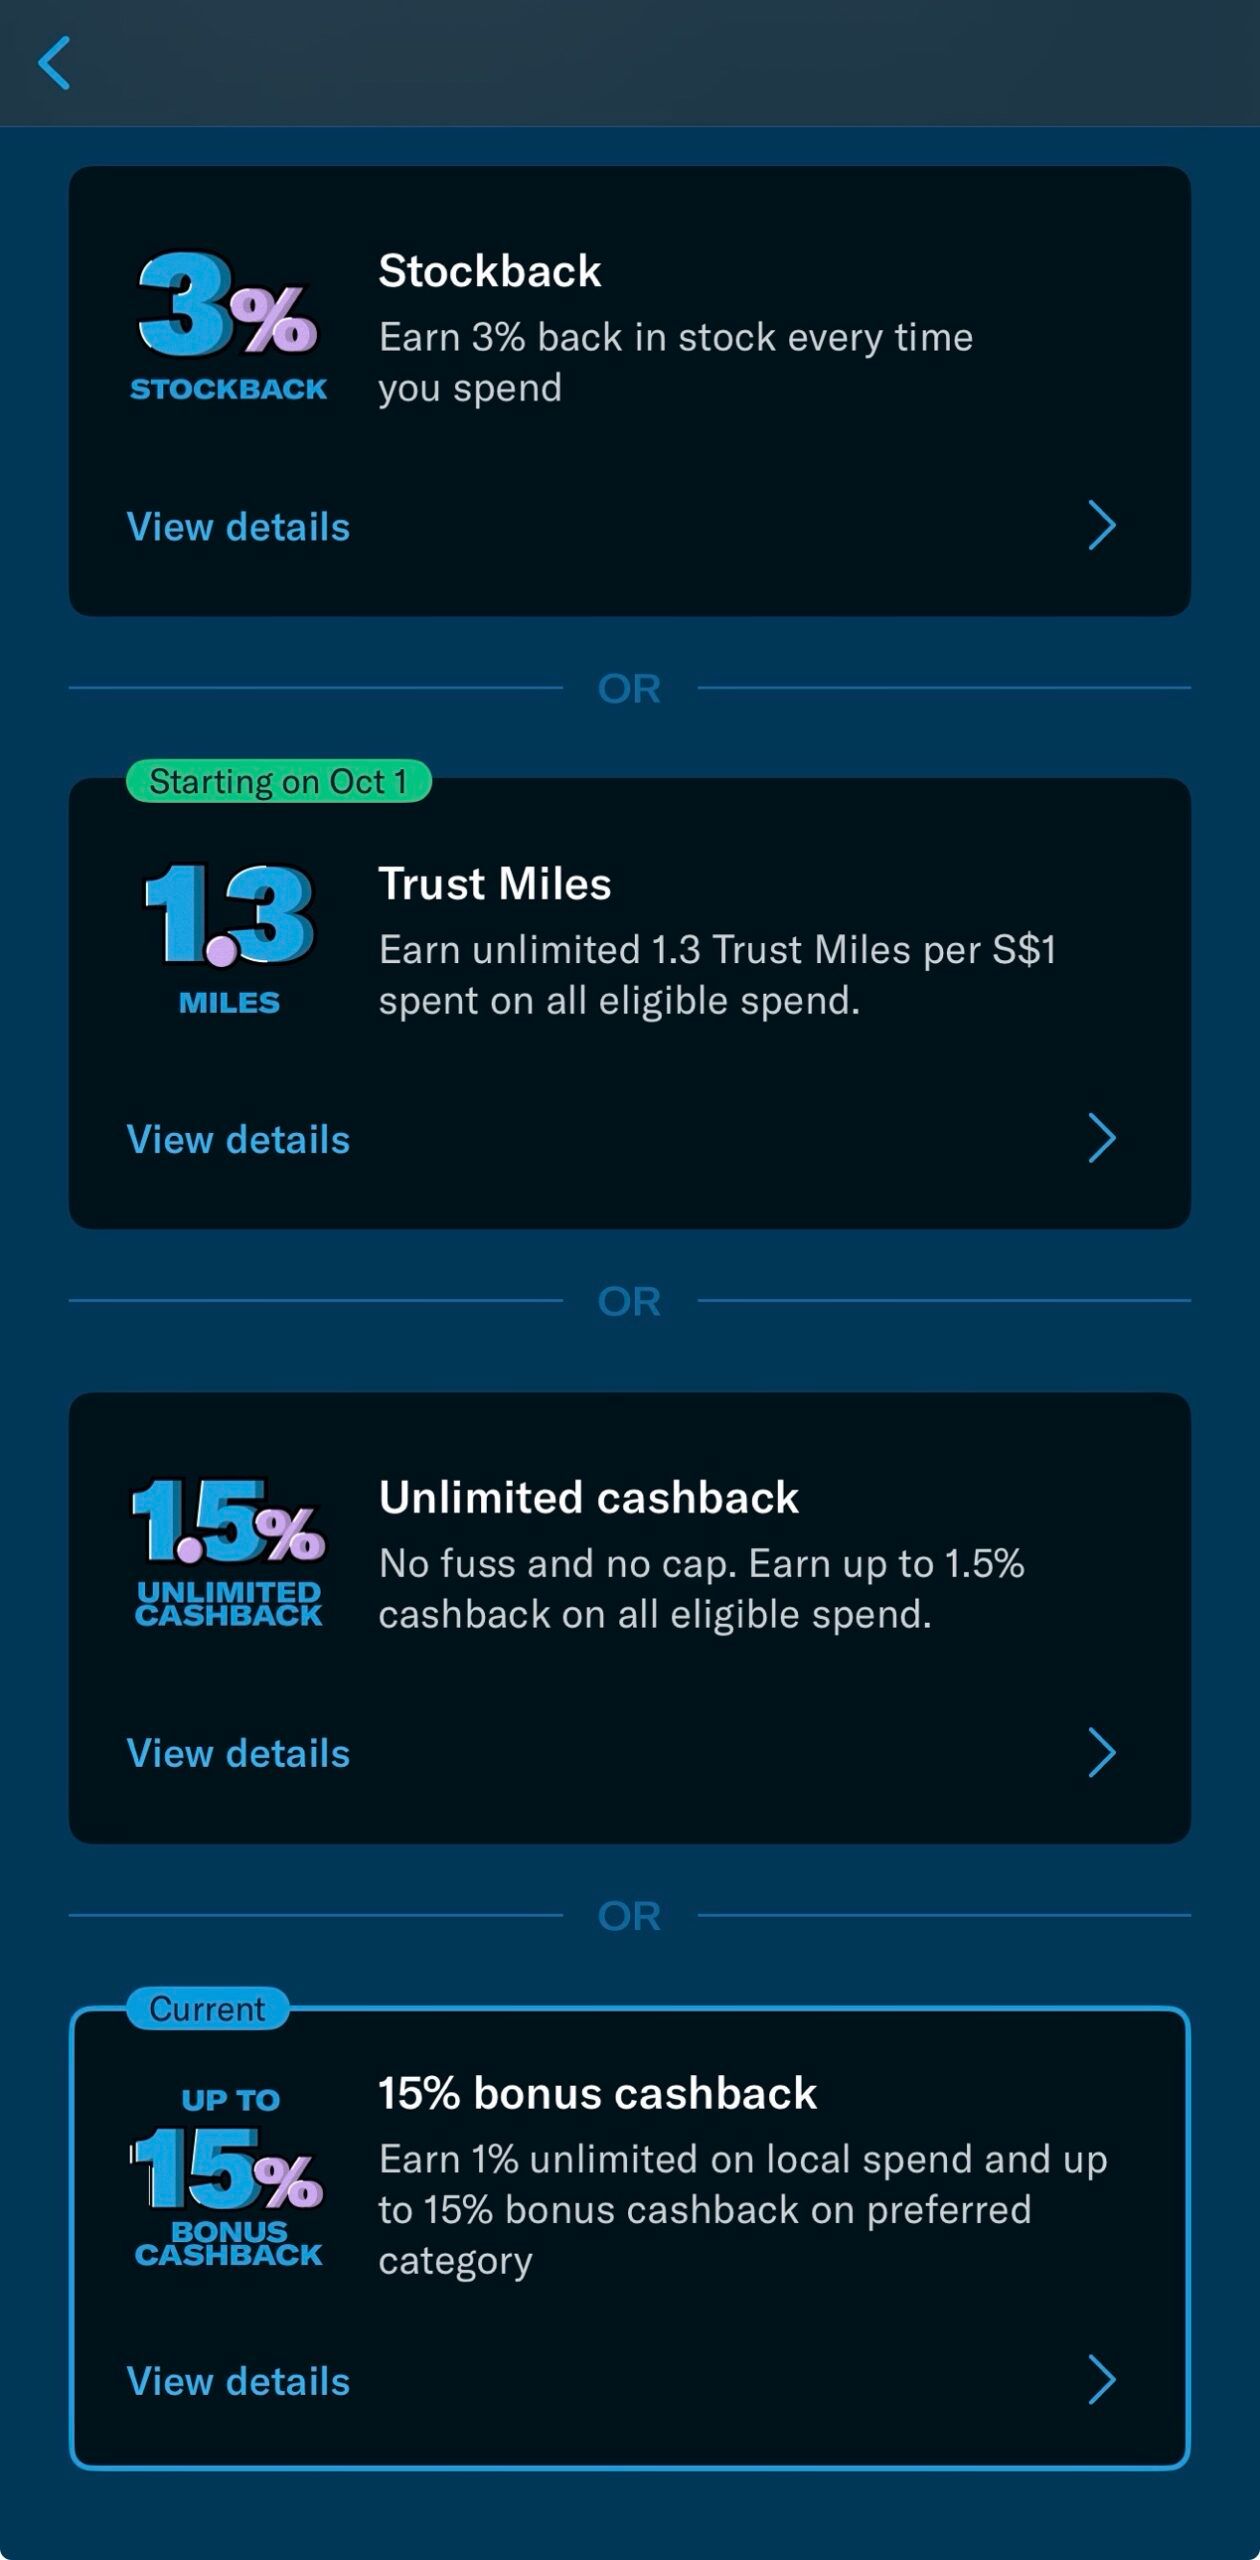
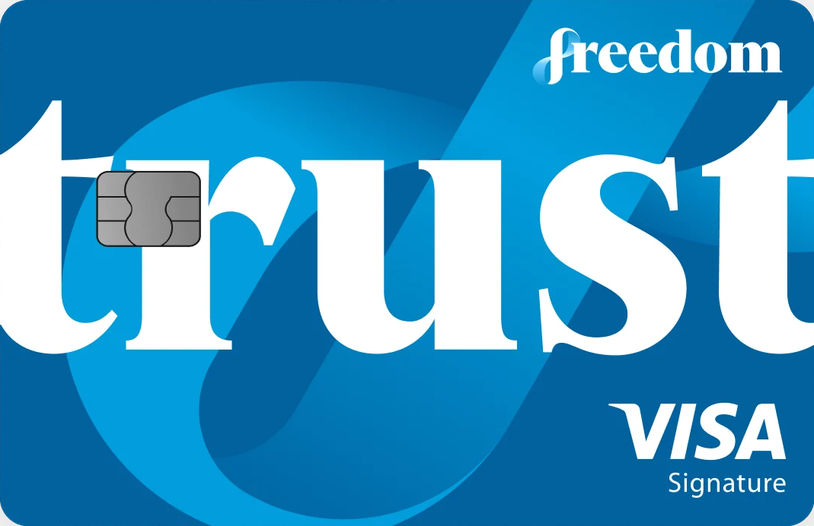
The Trust Freedom Card, previously called the Trust Cashback Card, now lets you choose between cashback, miles and rewards invested in US shares. It is issued by Trust, a Singapore digital bank, and has no annual fee. You can change your reward option each quarter.
Choose One of Four Ways to Earn Rewards
Choose one of these modes in the Trust app. I explain how each one works and who it suits below.
| Reward mode | What you receive | Who it suits |
|---|---|---|
| Unlimited Cashback | Cashback at a flat rate on eligible spending | You want cashback without a monthly spending target |
| Bonus Cashback | Base cashback plus a bonus on one chosen category | You can meet the spending requirement every month of the quarter |
| Stockback | Rewards used to buy part of a US share or fund | You want to invest your rewards and can open a TrustInvest account |
| Miles | Trust Miles to convert into KrisFlyer miles or Max Miles | You want flight rewards and can accumulate enough miles to justify the conversion fee |
FYS31XY4
- Download the app from the App Store or Google Play
- Copy the referral code above and enter into the app when prompted
- Sign up with your details
Choose Miles Before Your First Purchase for the Miles Welcome Offer
If you use the card without choosing a mode, your purchases earn Unlimited Cashback. If you are applying for the Miles welcome offer, Miles must be your first reward selection. Choose it before your first purchase; the eligibility rules and spending deadlines are in my Trust Bank welcome-bonus guide.


You can request a change in the app at any time, but it takes effect at the start of your next reward quarter. Each quarter is three consecutive months, starting from the month your card was approved.
Trust uses the purchase date to decide which reward mode applies. For example, if you buy something on 30 September under Unlimited Cashback and it posts on 2 October after you have switched to Stockback, that purchase still earns Unlimited Cashback.

Eligibility Requirements:
You must be at least 21.
| Applicant | Minimum yearly income |
|---|---|
| Singaporean or permanent resident aged 55 or younger | S$30,000 |
| Singaporean or permanent resident aged 56 or older | S$15,000 |
| Foreigner with a valid Singapore work pass | S$60,000 |
There is also a separate route for Singaporeans and permanent residents aged 56 or older who earn below S$15,000 a year. You may qualify for a card with a S$500 credit limit if you do not have a credit card or unsecured loan with Standard Chartered.
No Annual Fee or Foreign Transaction Fee
You do not pay a yearly fee just to keep the card, which is good for those who don’t really like to call the bank to ask for an annual fee waiver.
| Charge | What you pay |
|---|---|
| Annual fee | S$0 |
| Foreign transaction fee | S$0 |
| Replacement card | Currently waived; normally S$50 plus GST |
Some Bills Are Excluded, but Eligible Hospital Payments Can Earn Rewards
The following exclusions apply to all four reward modes and do not count towards the minimum spend for Bonus Cashback:
- Cash, transfers and payment channels: Cash advances, Trust loans, e-wallet and account top-ups, AXS, SAM and ATM payments, securities, cash-equivalent purchases, wire transfers and gambling.
- Bills and services: Insurance premiums, utilities, rent, school fees, government payments and donations, including political and religious donations. Building cleaning and maintenance under merchant category code (MCC) 7349, and miscellaneous services under MCC 7299, 7399 or 8999, are also excluded.
- Fees and transaction adjustments: Card fees, interest, refunds and transactions that have not posted.
Direct bus and MRT fares can earn rewards and fall under Transport for Bonus Cashback. Stored-value travel-card top-ups are excluded.
You can earn rewards on medical bills charged under MCC 8011 (doctors and physicians) or MCC 8062 (hospitals). These could be private hospitals (8062) like Raffles Hospital, Mount Elizabeth Novena Hospital, Mount Alvernia Hospital or some private clinics (8011) like Alliance Healthcare, Healthway Medical, Raffles Medical. However, it is hard to have accurate data on every single clinic in Singapore therefore the safest way is to use the DBS block card method to get the correct MCC before proceeding (below), if it’s worth doing. However, payments coded as MCC 9399 (government services) are excluded. Whether a hospital is public or private does not determine its MCC. Here is the list of Trust’s spending exclusions.
Check the Payment's MCC With a Temporarily Locked DBS Card
Before you start: In digibank, go to More → Manage Cards & Loans → Payment Controls. Select your DBS card, switch it off and tap Lock Now. Confirm it is locked, then attempt the payment through the hospital counter or payment portal you intend to use. The locked card should decline the payment. Different payment channels may have different MCCs.
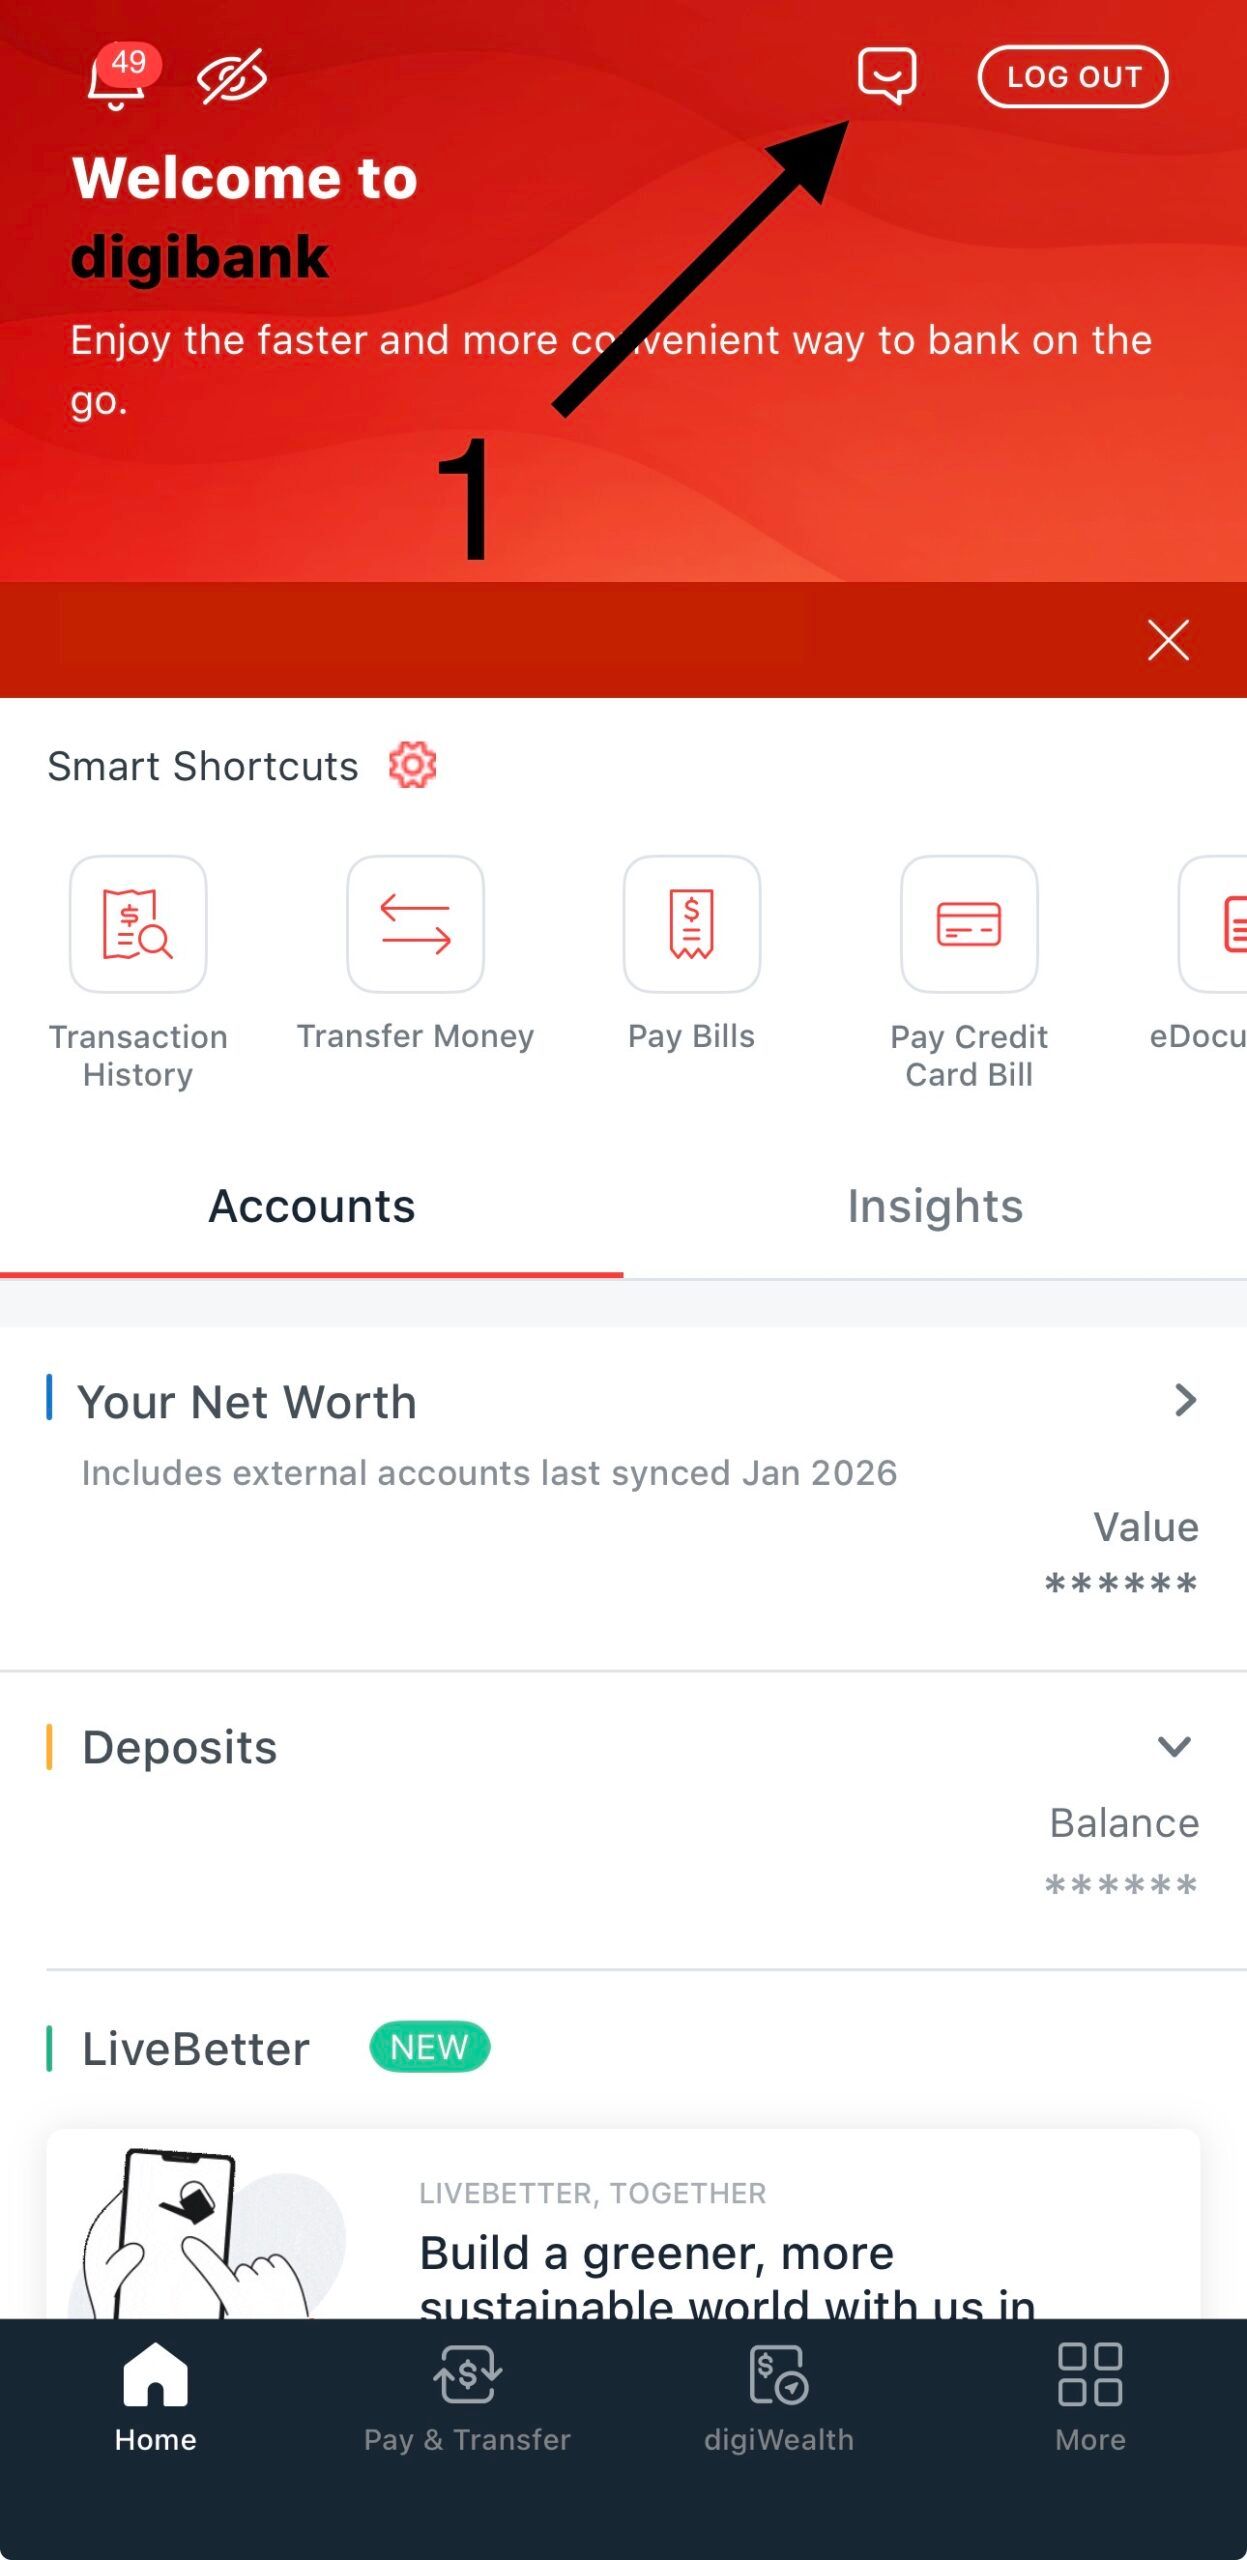
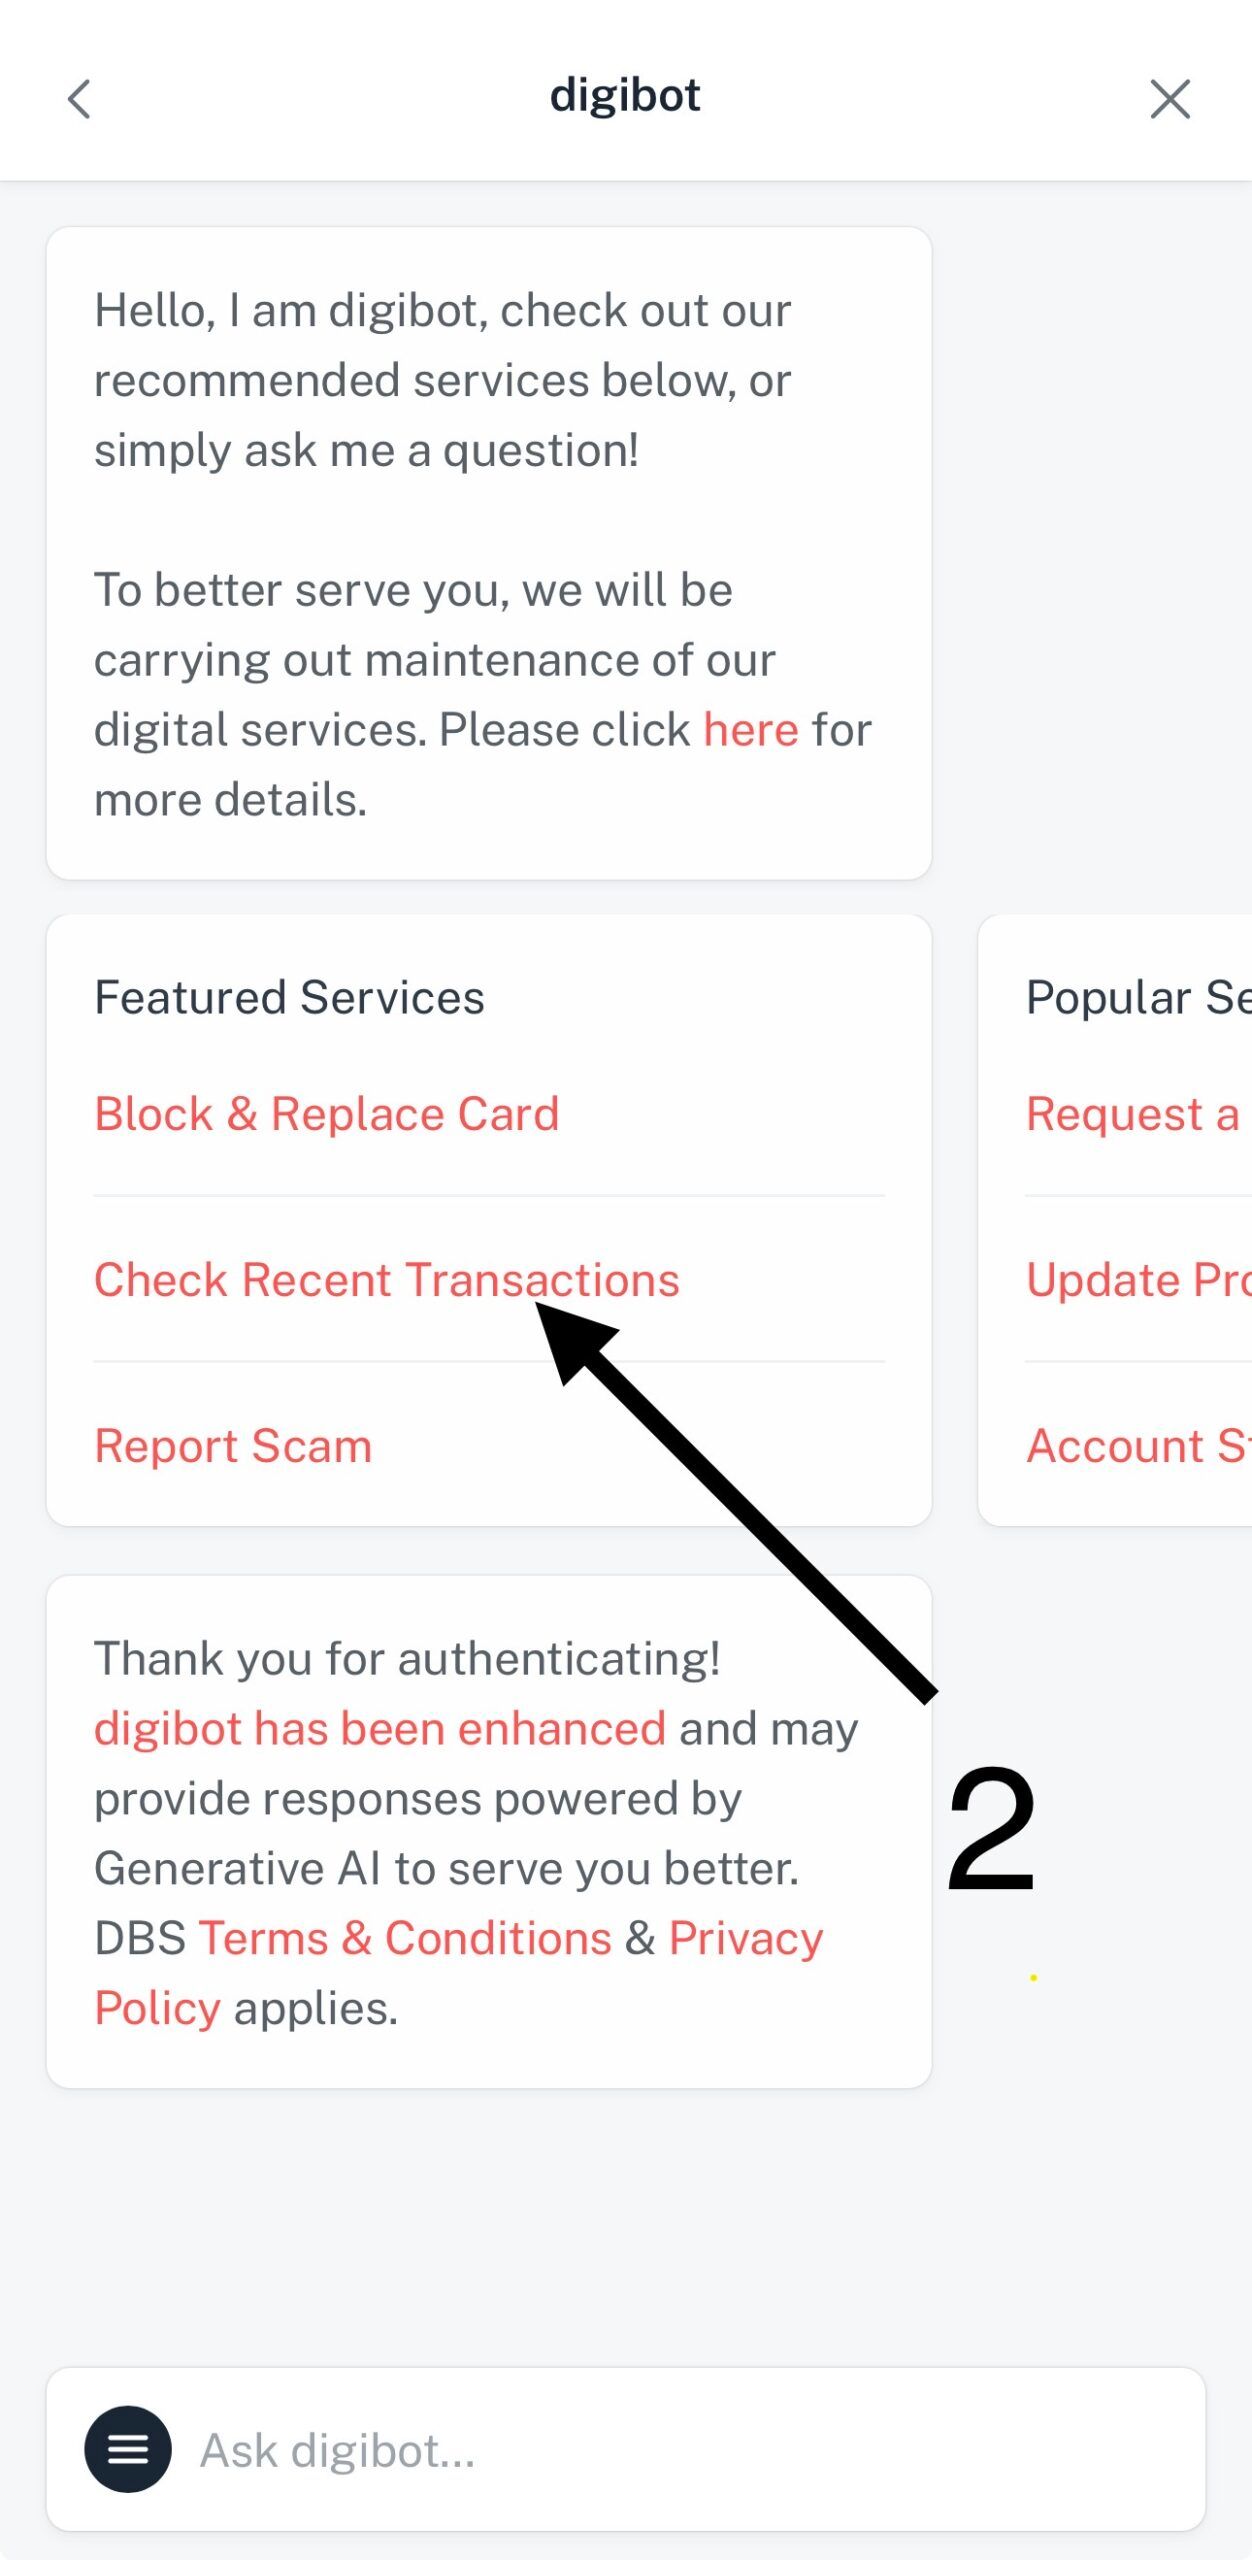
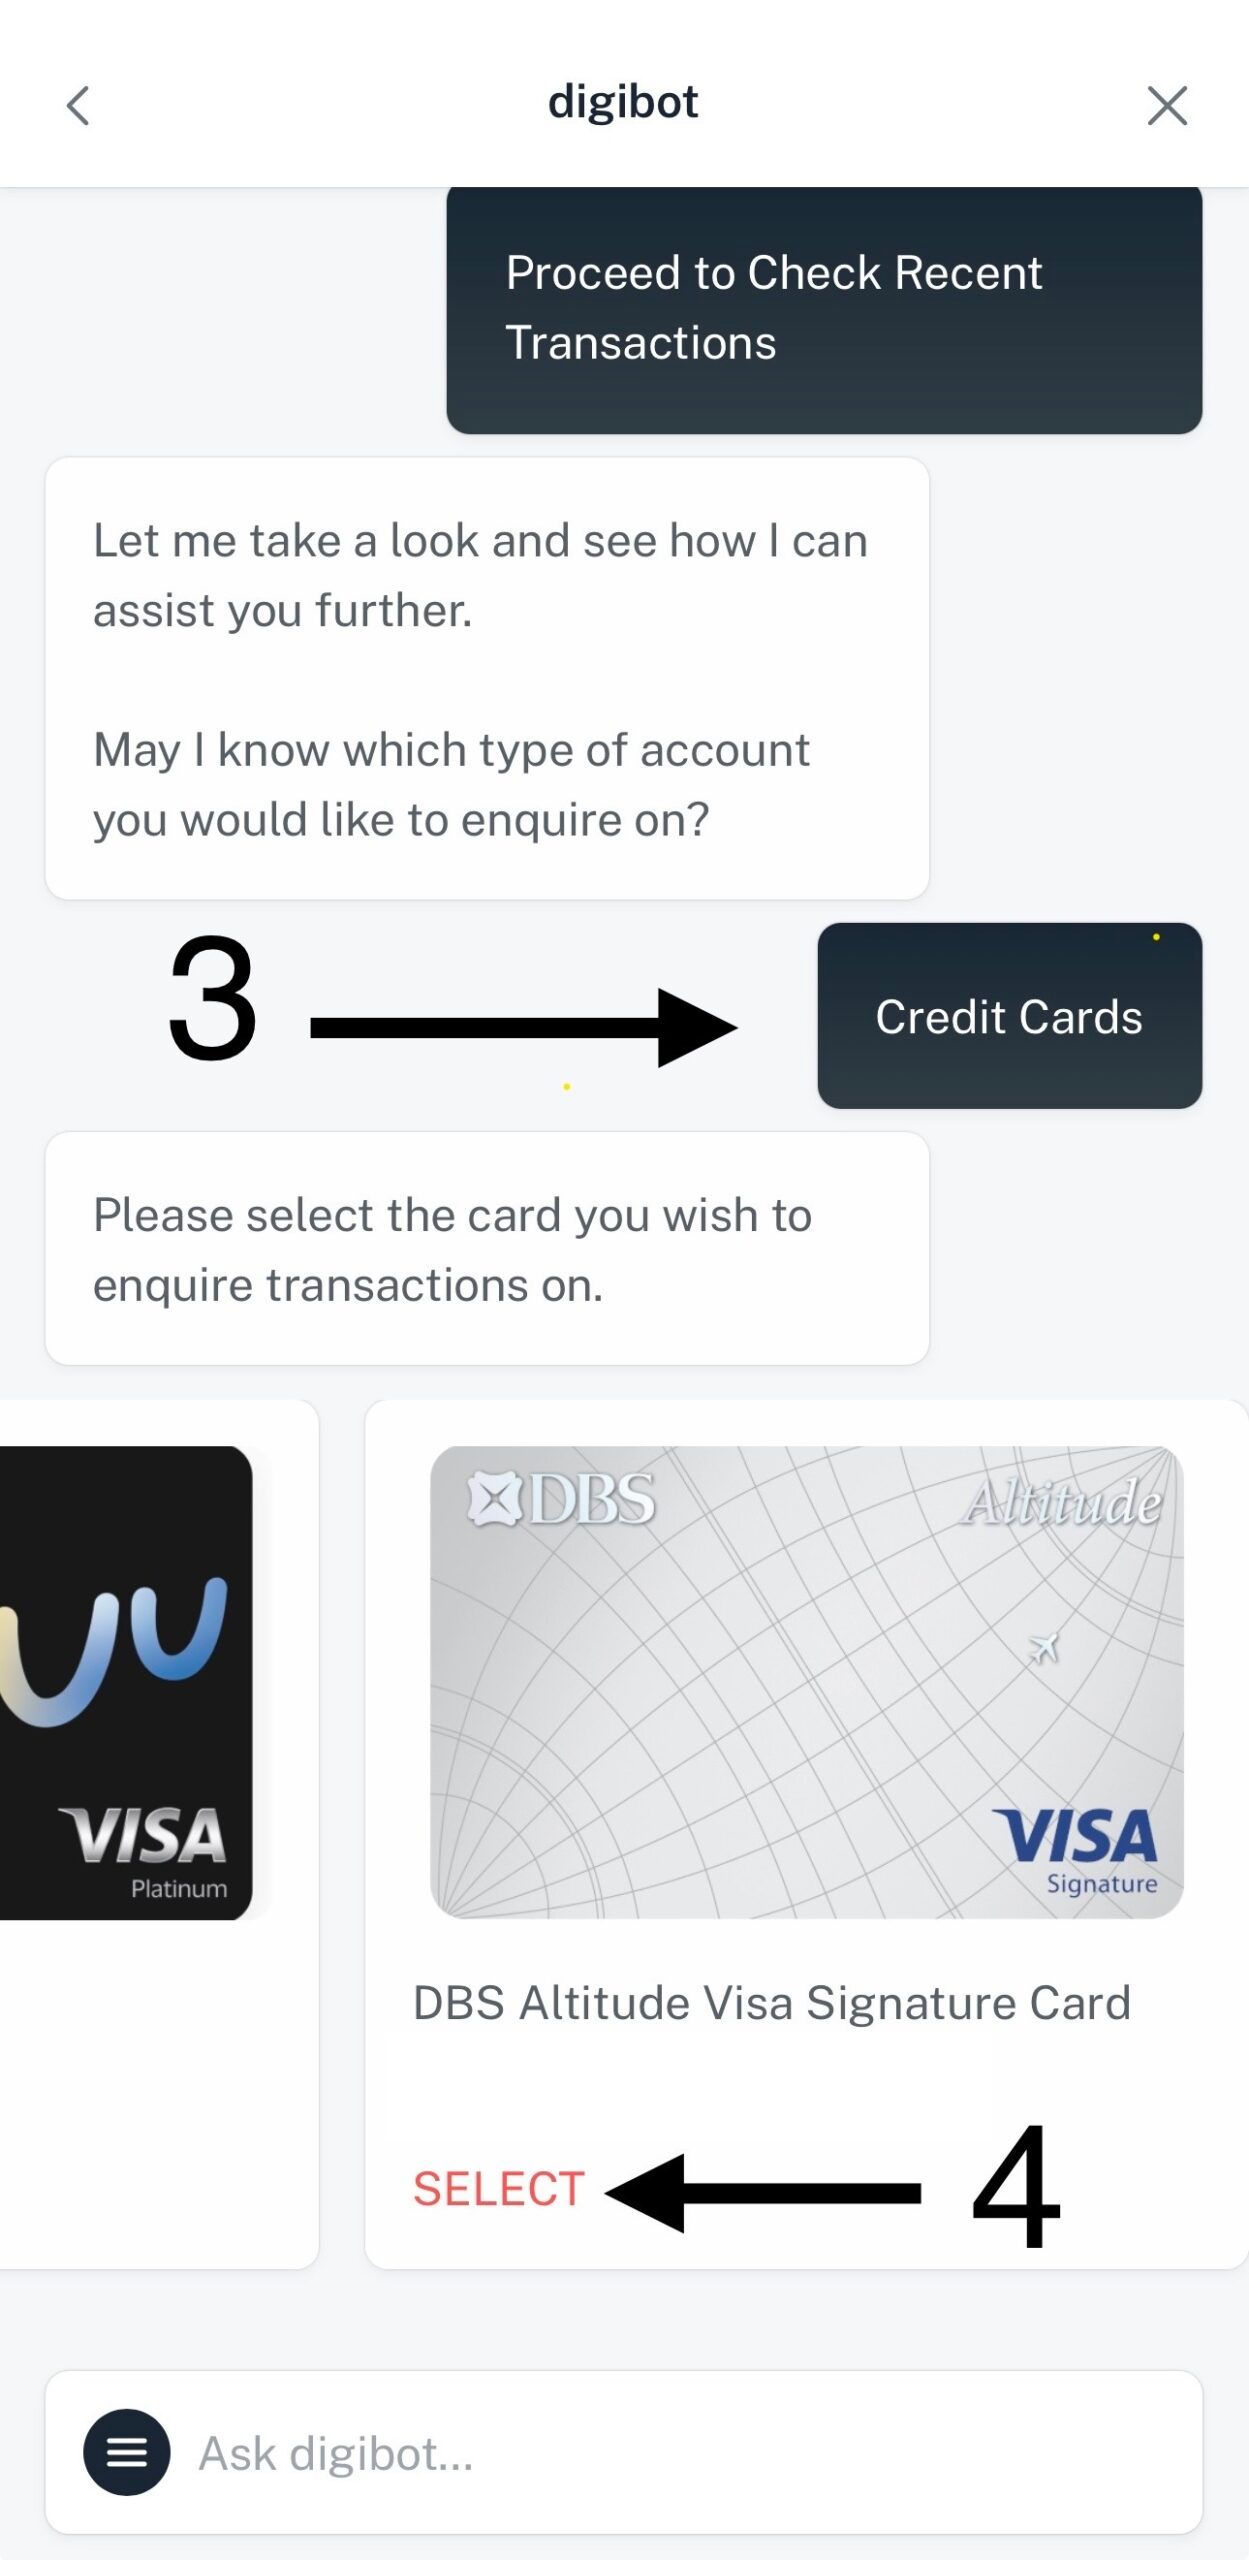
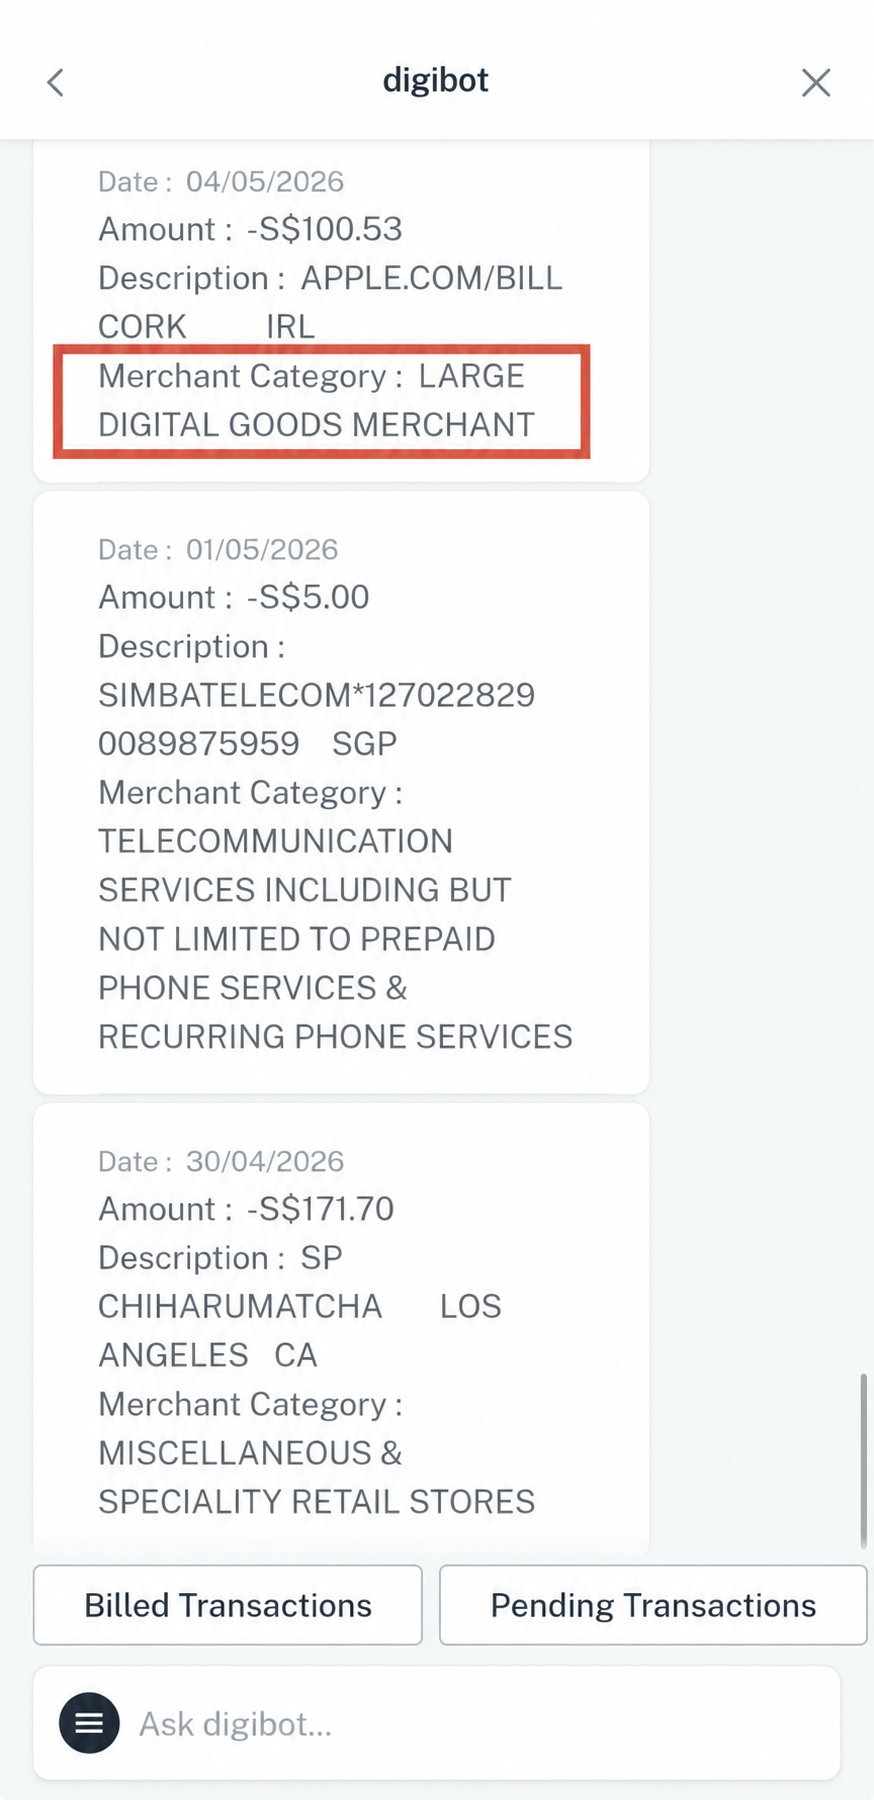
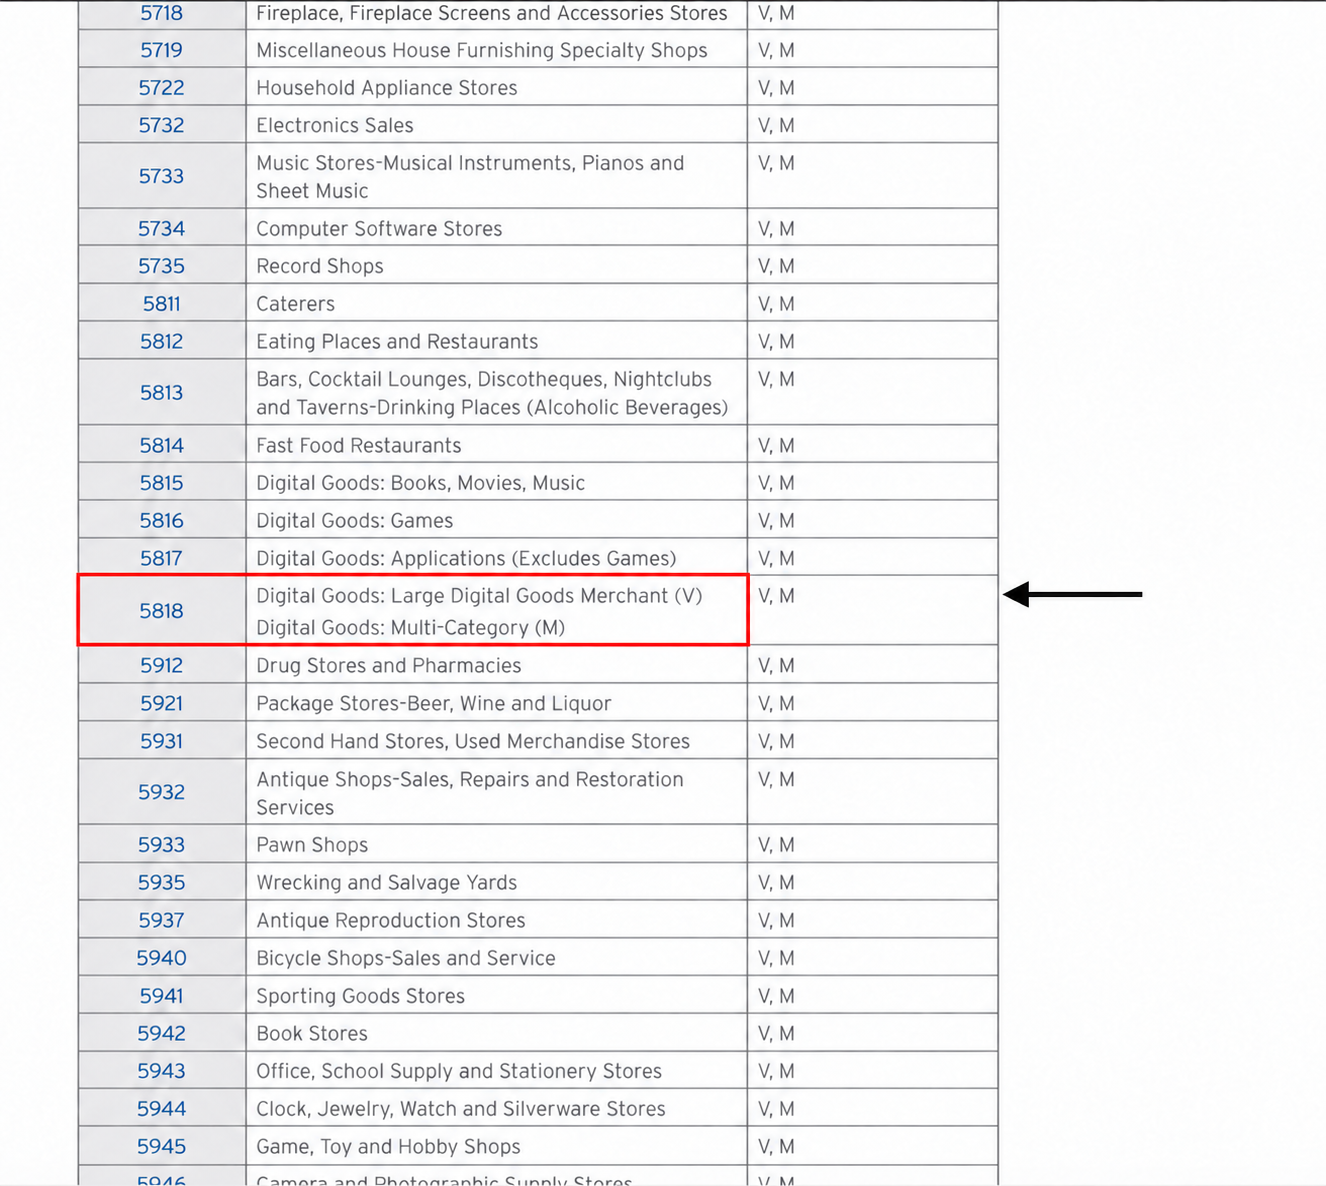
The numbers below match the arrows in the screenshots.
1. Tap the chat icon to open digibot. It is at the top right of the digibank home screen.

2. Tap Check Recent Transactions. Authenticate if prompted.

3. Tap Credit Cards.
4. Find the DBS card you used and tap SELECT.

5. Tap View Transaction History.
6. Choose Declined Transactions for the failed payment. This is the option DBS specifies for declined payments.
7. Read the Merchant Category for your payment. In this example, it is LARGE DIGITAL GOODS MERCHANT. This is an example from another purchase, not a hospital payment.

8. Open the Citibank MCC reference and find that category name. In this screenshot, it’s Digital Goods: Large Digital Goods Merchant.
9. Copy and paste to find the corresponding MCC code in the left column of the MCC reference file. 5818, the MCC for this example.

Check your payment’s code against Trust’s exclusions before paying with Trust. You can unlock your DBS card in Payment Controls when you want to use it again.
Choose How You Want To Earn Rewards With Your Trust Card
Jump to the section you need:
- Reward Mode 1 — Unlimited Cashback: Get Money Back Without a Monthly Spending Target
- Reward Mode 2 — Bonus Cashback: Earn Extra Cashback by Meeting Monthly Spending Targets
- Reward Mode 3 — Stockback: Invest Your Card Rewards in US Shares or Funds
- Reward Mode 4 — Miles: Turn Card Spending and Your Welcome Bonus Into Flight Rewards
- Redeem Your Welcome Codes in HeyMax
- How To Convert Your Spending Rewards from Trust Miles to Krisflyer Miles or HeyMax Miles for a Fee
- Use or Convert Your Rewards Before You Cancel the Card
Reward Mode 1 — Unlimited Cashback: Get Money Back Without a Monthly Spending Target
You earn 1.5% on eligible local spending and 0.5% on foreign spending, with no minimum spend or cap.
Compare How Much Cashback Other Cards Pay on Local Spending
| Card | Earn Rate | Min Spend & Cap | Notes | |
|---|---|---|---|---|
![]() UOB Absolute Cashback | 2%*Details | Min: none Cap: none | It is an American Express card, which many shops in Singapore do not accept. | Details |
| Earn Rate: 2% when you tap the physical card, till 31 January 2027; 1.7% otherwise | ||||
![]() DCS Ultimate Platinum | 2% | Min: none Cap: S$200/calendar month (S$10,000 of spend maxes it) | After the first 12 months, the S$10.90 monthly fee is waived if you make eight purchases or spend S$800 that month. Its foreign transaction fee is 2.25%, with up to 1% more. | Details |
![]() GXS Credit Card | 1.75% | Min: S$500/billing cycle (Grab spend doesn't count) Cap: none | You receive no base cashback if you miss the minimum spend. | Details |
![]() OCBC INFINITY Cashback | 1.6% | Min: none Cap: none | Details | |
![]() Citi Cash Back+ | 1.6% | Min: none Cap: none | Details | |
![]() Maybank FC Barcelona Visa Signature | 1.6% | Min: none Cap: none | Selected local medical, education, rental and business-services payments earn 0.3%. Utilities and SimplyGo are excluded. | Details |
![]() HSBC Advance | 2.5%*Details | Min: none Cap: S$70/calendar month (S$2,800 of spend maxes it) | The higher rate applies for that month alone; there is no three-month spending requirement. | Details |
| Earn Rate: 2.5% in a month you spend over S$2,000; 1.5% otherwise | ||||
![]() Mari Credit Card | 1.5% | Min: none Cap: none | Details | |
![]() Amex True Cashback | 1.5% | Min: none Cap: none | The merchant must accept American Express. | Details |
![]() Standard Chartered Simply Cash | 1.5% | Min: none Cap: none | Difficult to get annual fee waiver | Details |
* rate depends on certain conditions — tap the row for the full wording.
Spend S$500 locally on purchases that qualify for cashback and you’ll get S$7.50 with Trust, or S$8 with OCBC INFINITY or Citi Cash Back+. Therefore, my vote goes to OCBC Infinity that does the same job but gives a higher cashback card for general spending while supercharging your OCBC 360 Account savings with more interest.
The OCBC 360 Spend bonus requires at least S$500 of eligible card spending per calendar month; the interest you earn depends on how much you keep in the account.
With UOB Absolute, you can get S$10 cashback on the same S$500 spend under its 2% promotion. You’ll need to tap the physical card at a shop that accepts American Express. If not, you will receive the usual cashback rate of 1.7% which is still higher than Trust Card. DCS also gives S$10 at 2% cashback, but after the first year its S$10.90 monthly fee would wipe out that reward if you miss the fee waiver, which makes it a hassle to remember and track. See my DCS monthly-fee guide.
Compare Overseas Rewards on Cards With No Foreign Transaction Fee
Chocolate’s rewards are miles, not cashback. The flight values below assume you have enough miles to claim an eligible receipt in full through FlyAnywhere.
| Card | Earn Rate | Min Spend & Cap | Notes | |
|---|---|---|---|---|
![]() Mari Credit Card | 1.5%*Details | Min: none Cap: S$22.50/calendar month (S$1,500 of foreign-currency spending maxes it) | No foreign transaction fee. | Details |
| Earn Rate: 1.5% until 31 December 2027 | ||||
![]() Trust Freedom Card, Unlimited Cashback | 0.5% | Min: none Cap: none | No foreign transaction fee. | Details |
![]() UOB EVOL | 0.5%*Details | Min: none Cap: none | Promotion runs from 26 March to 31 December 2026 for principal-cardholder transactions. No foreign-exchange administrative fee on foreign-currency spending. UOB EVOL still charges 1% on Singapore-dollar transactions processed overseas; this is separate from its foreign-currency fee waiver. | Details |
| Earn Rate: 0.5% on eligible foreign-currency transactions processed in China and UOB's listed European countries; 1% on other eligible foreign-currency spending | ||||
![]() GXS Credit Card | 10%*Details | Min: none Cap: none | No foreign-exchange fee. GrabCoins are not cash. Grab wallet top-ups, PayLater and instalment payments are excluded. | Details |
| Earn Rate: 10% in GrabCoins on eligible overseas Grab rides/orders; no base cashback on other overseas purchases | ||||
![]() Chocolate Visa | 1 Max Mile per S$1*Details | Min: no spending minimum Cap: no total miles cap; the 1-mile rate applies only to the first S$2,000/calendar month | Debit card. Uses Visa's exchange rate with no fee markup. For spending from October 2026, keep an average daily balance of at least S$5,000 in Singapore dollars in your Chocolate Finance account during the previous calendar month. Need to link a verified HeyMax account using the same email address as Chocolate. | Details |
| Earn Rate: 1 Max Mile per S$1 on the first S$2,000/calendar month, then 0.4 Max Miles per S$1; about 1.8% and 0.72% respectively in FlyAnywhere flight value | ||||
* rate depends on certain conditions — tap the row for the full wording.
Spend S$1,000 in foreign currency on eligible purchases and you’ll get S$15 cashback with Mari, or S$5 with Trust’s Unlimited Cashback. Both have no foreign transaction fee. For cashback, Mari is the strongest choice within its S$1,500 monthly spending cap. After that cap, UOB EVOL’s 1% can beat Trust’s 0.5% on eligible transactions processed outside China and UOB’s listed European countries while its promotion runs; in those listed locations, EVOL’s 0.5% matches Trust.
GXS is the best for all eligible overseas Grab spend. Chocolate can suit you if you already keep the required S$5,000 balance and will use the miles for flights.
Reward Mode 2 — Bonus Cashback: Earn Extra Cashback by Meeting Monthly Spending Targets
This mode combines base cashback with a bonus on one category. The base rate is 1% on local spending and 0.5% on foreign spending. For the bonus, choose Dining, Shopping, Travel, Wellness, Transport or Entertainment. You can change that category each quarter.
Your total eligible card spending decides which tier you reach, including purchases outside your chosen category.
| Eligible spending required each month | Bonus on your chosen category | Quarterly bonus cap |
|---|---|---|
| S$500 | 5% | S$30; reached with S$600 of category spending |
| S$2,000 | 15% | S$250; reached with about S$1,667 of category spending |
Choose Bonus Cashback Only if your usual spending can meet the target every month, not just over three months in total.
Suppose September to November is a regular reward quarter, after your first quarter:
| Month | Your eligible spending | Tier reached that month |
|---|---|---|
| September | S$2,000 | Higher tier |
| October | S$500 | Lower tier |
| November | S$2,000 | Higher tier |
| Result for the whole quarter | October decides the tier | 5% category bonus, capped at S$30 |
To get the 15% category bonus in a regular quarter, you must spend at least S$2,000 in each of the three months. It is not an average: spending extra in one month cannot make up for another month below S$2,000. In this example, October falls to the S$500 tier, so the whole quarter gets the lower 5% category bonus and S$30 bonus cap.
Choose Trust Only If You Are Comfortable With Max Achievable Cashback of 5.17% for S$2,000 Monthly Spend in 3 Consecutive Months
Suppose you choose Dining and spend S$600 on dining plus S$1,400 on other eligible local purchases each month. You meet the S$2,000 monthly target. Your other category choices are Shopping, Travel, Wellness, Transport and Entertainment.
For a regular reward quarter after your first quarter, the calculation is:
| Spending category | Spending over three months | Base cashback at 1% | Category bonus | Total cashback |
|---|---|---|---|---|
| Dining, your chosen category | S$1,800 | S$18 | S$270 at 15%, capped at S$250 | S$268 |
| Other eligible local purchases | S$4,200 | S$42 | S$0 | S$42 |
| Total | S$6,000 | S$60 | S$250 | S$310 |
You receive a maximum achievable cashback rate of S$310 on S$6,000 of spending, or 5.17%. This follows Trust’s cashback rates and quarterly cap. The advertised 15% bonus applies only to your chosen category and stops at S$250; it is not 15% back on the full S$6,000.
How Does It Compare To Other High Earn Rate Cashback Cards In The Market?
| Card | Earn Rate | Min Spend & Cap | Notes | |
|---|---|---|---|---|
![]() UOB EVOL | Up to 6.36%*Details | Min: S$800 per statement month Cap: S$30 shared by eligible local online/mobile contactless; S$20 shared by selected gym/telco/streaming; S$30 for other eligible local spending | A lower monthly target can give a higher overall return. Savings interest: UOB One Account: S$500 eligible card spending per calendar month meets the card-spend condition. | Details |
| Earn Rate: Up to 6.36% overall on S$800 of local spending with the right category mix | ||||
![]() Trust Freedom Card, Bonus Cashback | 5.17%*Details | Min: S$2,000 every month for three months Cap: S$250 category bonus for that quarter, plus base cashback | Works when you already spend S$2,000 each month and earn the full category bonus. The 5.17% example uses all S$250 of that bonus on S$6,000 of local spending. Savings interest: Trust Savings: five qualifying purchases of at least S$30 each, posted within the month. | Details |
| Earn Rate: 5.17% max achievable cashback overall in the S$6,000 local-spending example above | ||||
![]() HSBC Live+ | 5%*Details | Min: S$600 every calendar month of the quarter Cap: S$250 cashback for the whole quarter | A lower monthly target, with rewards across several categories instead of just one chosen category. | Details |
| Earn Rate: 5% max achievable cashback on eligible dining, shopping, entertainment and selected petrol; 0.3% on other eligible spending | ||||
![]() Citi SMRT | 5%*Details | Min: S$500 per statement month Cap: S$600 cashback per 12-month card period | A lower spending target and an annual cap can suit large eligible online purchases. Online travel and mobile-wallet payments are excluded | Details |
| Earn Rate: 5% max achievable cashback on eligible groceries, online purchases, SimplyGo and taxis/private-hire rides | ||||
![]() Maybank Family & Friends | 6%*Details | Min: S$800 per calendar month Cap: S$20 cashback per chosen category; increases to S$30 per category when you spend S$1,600 | A lower monthly target and five chosen categories can suit spending spread across different purchases. | Details |
| Earn Rate: 6% when you spend S$800 a month; 8% when you spend S$1,600, except groceries stay at 6% | ||||
![]() OCBC 365 | 5%*Details | Min: S$800 per calendar month Cap: S$80 cashback that month; increases to S$160 when you spend S$1,600 | A lower target that you meet one month at a time, with rewards across several everyday categories. Savings interest: OCBC 360: S$500 eligible card spending per calendar month meets the Spend bonus condition. | Details |
| Earn Rate: 5% qualifying dining, 6% petrol and 3% eligible groceries, land transport and selected recurring/lifestyle payments until 31 October 2026 | ||||
![]() UOB One | Up to 3.33%*Details | Min: S$600, S$1,000 or S$2,000, plus ten transactions, in each statement month for three months Cap: S$60, S$100 or S$200 cashback respectively for the quarter; extra cashback capped at S$120 per statement month | A lower starting target and general cashback can suit spending across different categories. Savings interest: UOB One Account: S$500 eligible card spending per calendar month; separate from the card’s cashback targets. | Details |
| Earn Rate: Up to 3.33% general cashback, plus extra rewards at selected merchants and on groceries | ||||
* rate depends on certain conditions — tap the row for the full wording.
My Take
For everyday purchases paid online or by mobile contactless, UOB EVOL is my preferred option if I can meet its S$800 statement-month target. The eligible categories are easier to hit with up to 6.36% cashback on an all-local spending mix under UOB’s category caps, while Trust’s bonus applies to one chosen category and requires S$2,000 every month for three months with a maximum achievable cashback of 5.17%. If you use a UOB One Account, qualifying EVOL spending can also meet its card-spend condition for savings interest.
Maybank Family & Friends would be my second option if I do not bank with UOB and my purchases fit its categories. You choose five categories and need S$800 a calendar month for 6%, capped at S$20 per category. At S$1,600, selected categories earn 8% with a S$30 cap per category; groceries remain at 6%. It can be easier to qualify than Trust, but spreading purchases across your chosen categories matters because unused cashback capacity in one category does not increase another category’s cap.
I like Citi SMRT for eligible online purchases, especially large ones. Online travel purchases such as hotels, flights and car rentals, as well as mobile-wallet payments, are excluded. You need to spend S$500 per statement month to earn 5%, but the S$600 cashback cap lasts for your 12-month card period. That allows up to S$12,000 of eligible spending at 5% across that period, rather than a small cashback cap each month. I explain this in my Citi SMRT review.
Reward Mode 3 — Stockback: Invest Your Card Rewards in US Shares or Funds
Stockback turns your rewards into part of a US share or fund that you choose in the Trust app.
| When you spend | Local spending | Foreign spending | Reward cap |
|---|---|---|---|
| Until 31 December 2026 | 3% | 3% | S$500 per quarter |
| From 1 January 2027 | 2% | 0.5% | S$500 per quarter |
There are around 50 choices, including Apple, Microsoft, NVIDIA and Tesla, as well as index funds that hold several companies.
You need an active Trust savings account to open the separate TrustInvest account that holds the investments. US persons cannot use Stockback. This includes US citizens, green card holders and people treated as US tax residents because of the number of days they have spent there.
Trust Automatically Invests Your Rewards When They Reach S$10
Each time your Stockback rewards reach S$10, Trust converts the amount to US dollars and buys a small part of the investment you chose. You do not have to place the order yourself. It should appear in your portfolio within five business days. If the market is closed, the purchase waits until a trading day.
Until you reach S$10, the rewards stay in your Stockback balance. The terms do not promise interest on this balance.
Stockback rewards earned on 28 December 2026 expire on 31 December 2027 if they remain unused, not a few days later. The expiry date is the end of the following calendar year. Switching reward modes does not shorten that period, and investments already bought do not expire.
Trust or its appointed custodian holds the investments for you, possibly together with other customers’ investments in a pooled account. You can keep or sell them through Trust, but you cannot move them to another broker. See the Stockback FAQ and TrustInvest terms.
Small Share Sales Can Lose a Large Percentage to Fees
Trust charges no commission or market fees when it automatically buys investments with your Stockback rewards. It also charges no custody, platform or settlement fees.
Selling is different. The commission is waived until 31 December 2026. From 1 January 2027, you pay 0.05% of the amount sold, with a minimum of US$2.99 for each sale.
That minimum matters for small amounts. Sell US$10 of shares and the commission alone is US$2.99, or 29.9%. Sell US$100 and it is still US$2.99, or 2.99%.
There is also a US regulatory selling fee of 0.00206%, with a US$0.01 minimum, including during the commission waiver. 9% GST applies to fees where required. The fee schedule lists the charges and waivers.
If you convert the sale proceeds back to Singapore dollars, Trust uses its own exchange rate and may charge a conversion fee. These costs are on top of the commission in the examples above, so the US-dollar sale amount is not the amount you will receive in Singapore dollars.
Choose Stockback if You Are Comfortable Keeping Investments With Trust
Choose Stockback if you are comfortable keeping the investments with Trust. You can sell them, but you cannot transfer the shares to another broker. That makes it less suitable if you want to collect small rewards and immediately turn them into cash, especially after the commission waiver ends. You also need to watch an unused balance below S$10, which can expire before it is invested.
Reward Mode 4 — Miles: Turn Card Spending and Your Welcome Bonus Into Flight Rewards
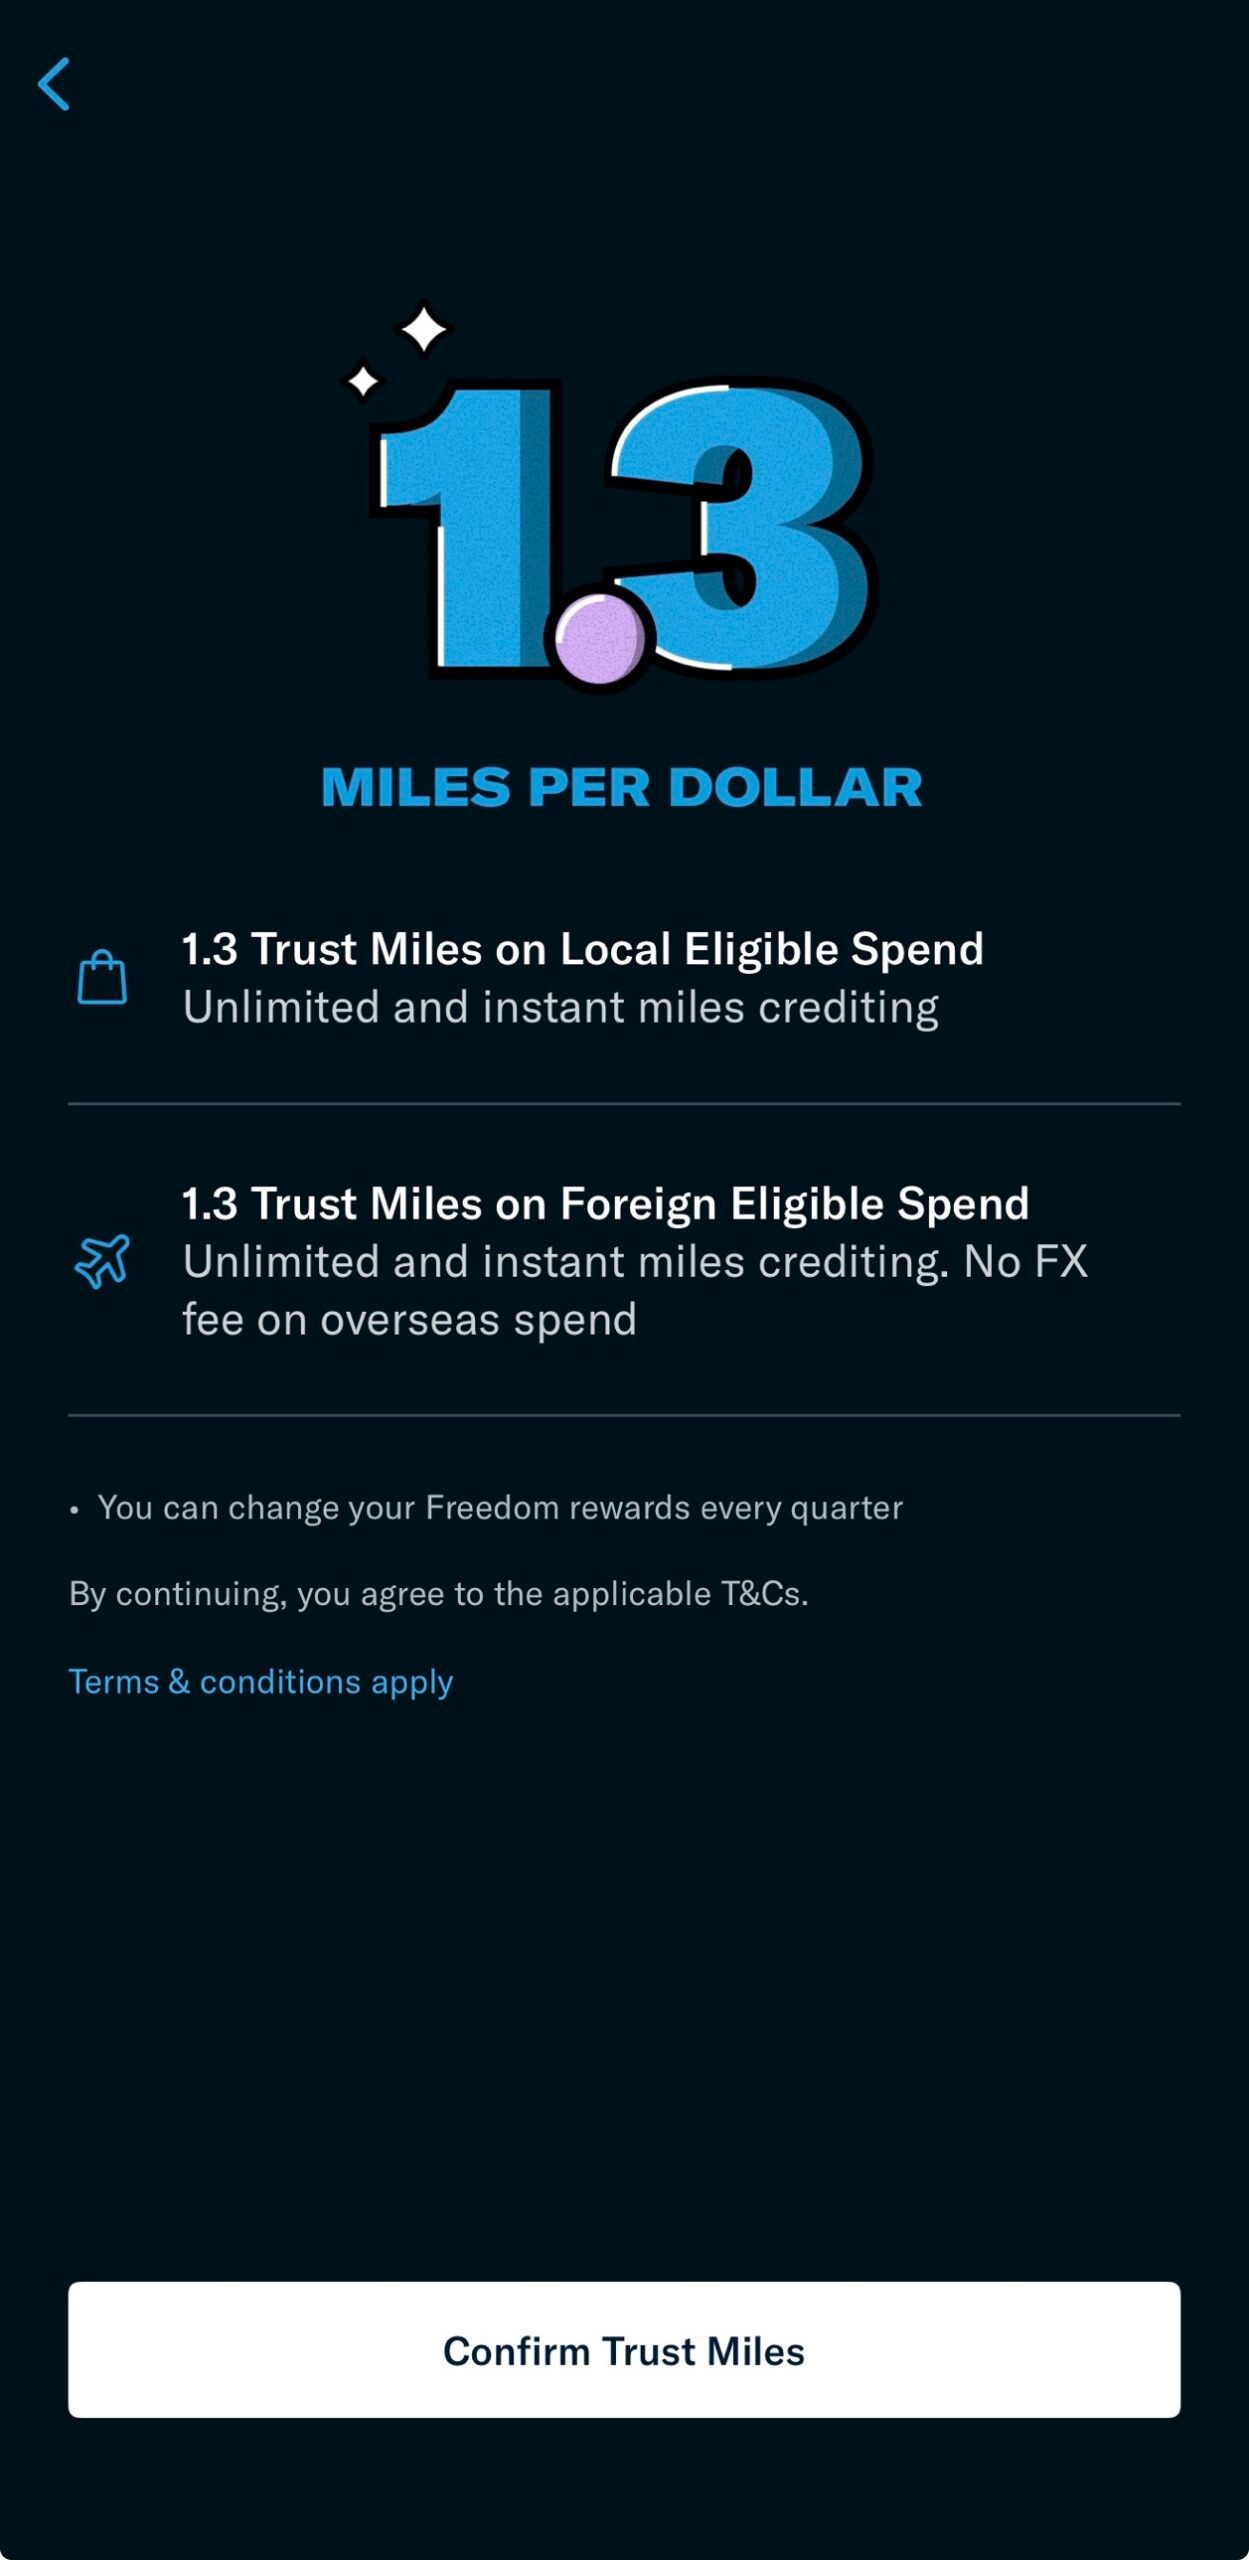
Miles mode earns 1.3 Trust Miles per S$1 on eligible local and overseas spending, with no minimum spend or cap.
Trust awards miles for each purchase in complete S$5 blocks:
| Purchase amount | Complete S$5 blocks | Trust Miles earned |
|---|---|---|
| S$12 | 2 | 2 × 6.5 = 13 |
| S$4.99 | 0 | 0 |
The remaining S$2 from the first purchase is not combined with the second purchase to earn more miles. See the official miles FAQ.
Spending Miles and Welcome Miles Are Redeemed Differently
The miles from spending and the welcome bonus follow different redemption processes:
| Where the reward comes from | What you receive | How you redeem it |
|---|---|---|
| Eligible spending in Miles mode | Trust Miles in the Trust app | Convert to KrisFlyer miles or Max Miles; a conversion fee of S$27.25 including GST applies |
| Miles Welcome Offer approved 21 September–31 October 2026, by 11:59pm Singapore time | Codes for Max Miles once Quest is completed | Enter each code in HeyMax; no Trust Miles conversion or conversion fee is needed |
KrisFlyer is Singapore Airlines’ miles programme. HeyMax is a Singapore rewards app, like a miles version of ShopBack, and its points are called Max Miles.
You need a HeyMax account for the welcome bonus codes or to convert Trust Miles into Max Miles. If you only want to convert your spending rewards to KrisFlyer, you can do that directly in Trust without HeyMax.
If you have a welcome bonus code, you can refer to the step by step guide in Trust Bank Is Giving Up to 100,000 Max Miles on the Trust Freedom Card — Here’s How to Get It.
For flight comparisons and redemption steps, I’ll be writing a guide for that soon. Stay subscribed to my Telegram channel.
How To Convert Your Spending Rewards from Trust Miles to Krisflyer Miles or HeyMax Miles for a Fee
In the Trust app, open Rewards → My earnings → Freedom card → Miles → Redeem your miles. Choose your destination and enter the number of partner miles you want.
| Partner | Miles you receive | Account required before converting |
|---|---|---|
| Singapore Airlines | KrisFlyer miles | Your own KrisFlyer account; enter your membership number on your first conversion |
| HeyMax | Max Miles | Your own HeyMax account; enter your membership ID on your first conversion |
If you choose Max Miles, your HeyMax membership ID is at the top of the Profile screen.
| Conversion rule | Details |
|---|---|
| Rate | 1 Trust Mile = 1 partner mile |
| Minimum | 1 partner mile |
| Fee | S$27.25 including GST per conversion, charged to your Trust Freedom Card |
| Crediting | Instant |
| Account holder | The destination account must be in your own name |
| Cancellation | A submitted conversion cannot be cancelled or refunded |
| Trust Miles expiry | End of the third calendar year after the year earned; miles earned in 2026 expire after 31 December 2029 |
Your earned Trust Miles stay in your account when you switch reward modes. You can redeem them before they expire.
Every conversion has its own fee, so splitting your balance between KrisFlyer and Max Miles means paying twice.
For example, S$10,000 of eligible card spending earns up to 13,000 Trust Miles, depending on transaction rounding. Converted to Max Miles, that is up to S$234 towards flights through FlyAnywhere. Subtract the S$27.25 conversion fee from S$234 and you have S$206.75, or about 2% of what you spent, provided you can use the miles for a qualifying full-receipt claim. This uses the official earning and rounding rules and Trust’s conversion fee.
Linking Your Card to Track Spending in HeyMax Is Optional
You can link your Trust Freedom Card through Profile → My cards to track its spending with HeyMax’s CardMaximiser. Your Trust rewards continue to earn without this link, and linking is not required for welcome codes or FlyAnywhere.
Use or Convert Your Rewards Before You Cancel the Card
Your card must have no outstanding balance or pending transactions before you close it. Deal with your rewards first:
| Reward mode | What to do before closing the card |
|---|---|
| Unlimited Cashback | Use your cashback to offset outstanding card spending before you close the card. |
| Bonus Cashback | Use cashback already credited to offset outstanding card spending before you close the card. |
| Stockback | An accumulated balance below S$10 is forfeited. Shares already bought remain in your investment portfolio, and pending allocation orders will be completed. |
| Miles | Convert the Trust Miles you want to keep before closing the card. Any unconverted Trust Miles are forfeited. |
Final Thoughts:
I would choose Miles for the current welcome offer if I could meet the spending requirement with purchases I already planned. You need to open a HeyMax account and redeem the codes, but the extra steps can be worthwhile for the flight rewards.
Log in to HeyMax at least once every 12 months to keep your Max Miles valid. Leaving the app signed in does not count as a new login, according to HeyMax’s account activity rules.
After earning the welcome bonus, choose your ongoing reward mode based on your usual spending:
- Unlimited Cashback: you want money back without a monthly spending target.
- Bonus Cashback: you already spend S$2,000 each month and enough in your chosen category to earn the full quarterly bonus. Compare the lower-spend alternatives above first.
- Stockback: you want your rewards invested and are comfortable keeping those investments with Trust.
- Miles: you want flight rewards and can accumulate enough Trust Miles to make the S$27.25 conversion fee worthwhile.
You can change your reward mode each quarter, so choosing Miles for the welcome offer does not lock you into it. For local and overseas cashback, I would choose the other alternatives above. I would consider Trust for Stockback if I wanted to invest my rewards, or Miles if I planned to use them for flights.
💳 Credit cards change their T&Cs every so often and it’s difficult to stay updated. That’s why I created a Telegram Broadcast where you can receive timely bite-sized updates.
Audz, your lobang sis - sharing personal finance to achieve happiness, prosperity and progress for us all.